CoWoS Expansion: What Substrate Capacity Means for PCB Suppliers
At the start of September 2026, reports described monthly output of one hundred and thirty thousand units behind the expansion of chip-on-wafer-on-substrate capacity, and separately indicated that a leading foundry is widening the scope of work outsourced to packaging and test partners. Work previously kept in-house is now being shared more broadly, while the largest substrate formats continue to move into production. CoWoS expansion on that scale is what turns substrate capacity into a PCB supply question.
CoWoS is the packaging approach that places high bandwidth memory and logic dies on a silicon interposer, which then mounts on a substrate that connects to the system board. Every layer in that stack must be produced in sufficient quantity for the whole assembly to ship, and that is where the interest for board and substrate manufacturers lies.
The capacity of one step does not help if another step is short. Announcements about interposer capacity, substrate capacity and assembly capacity therefore have to be read together, and the binding constraint moves between them as each is expanded.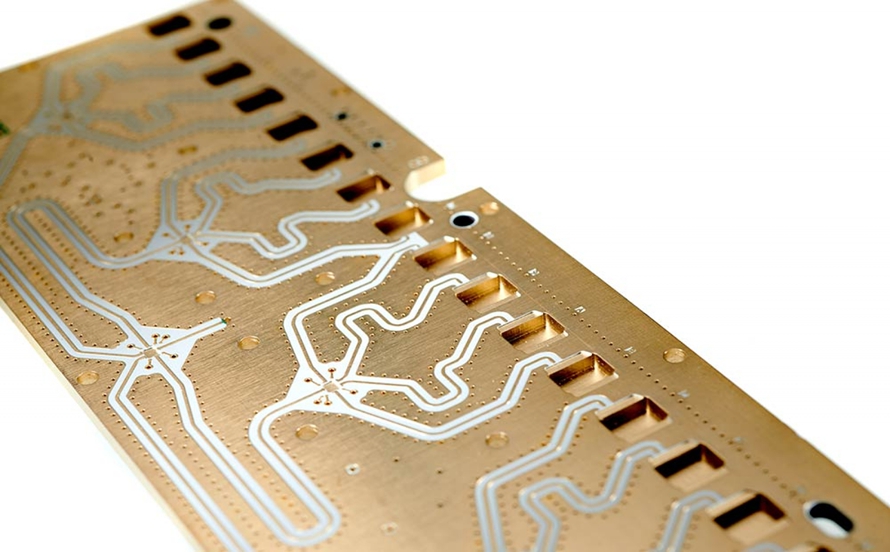
Where the Constraint Moves Next
When interposer capacity was the limiting factor, investment flowed there. As that capacity arrives, the constraint moves to the substrate, and then possibly to test. The pattern is familiar from earlier packaging generations: capital follows the bottleneck, and the bottleneck relocates once the capital lands.
Substrates are a plausible next constraint because they are difficult to build and their capacity cannot be added quickly. A substrate for a large artificial intelligence package requires fine redistribution layers, low warpage across a large area and a material system that can survive the assembly thermal profile. Those requirements limit the number of factories able to participate.
That is precisely why substrate announcements have become a leading indicator for the broader electronics supply chain. A commitment to build substrate capacity signals an expectation about package volumes a year or more ahead, and it usually precedes corresponding demand for the boards those packages mount on.
Geography plays a role in the expansion pattern. Substrate and packaging capacity is concentrated in a small number of regions, and each new line requires a supply chain of materials, equipment and skilled technicians around it. Building capacity without that ecosystem produces equipment that runs below its potential, which is one reason announced capacity and effective capacity differ.
Finally, the economics of the whole stack matter more than any single step. A package ships when every layer is available, so the value of additional capacity at one stage depends on whether the downstream stage can absorb it. Suppliers who model the chain rather than their own step are better able to time their investments, and customers are better served by asking for that view than by negotiating individual lead times.
Why Substrates Are Hard to Scale
A substrate is a printed circuit board refined to extremes. Line widths and spacing are far smaller than on a conventional board, layer counts are high relative to thickness, and the dielectric must be extremely uniform because the features are dense and the electrical requirements are strict. The manufacturing tolerance for warpage across the panel is tight enough to reject material that would pass on an ordinary product.
Equipment and materials are both specialised. Build-up films come from a small group of suppliers, and their availability has already constrained the industry. The imaging, plating and inspection equipment needed for fine features is different from what a conventional board line uses, and lead times for that equipment are long.
That combination means substrate capacity is added in steps of years rather than months. A factory cannot convert an existing board line into a substrate line quickly, and a new line takes time to reach acceptable yield. Capacity announcements should therefore be read as commitments with a delivery date, not as immediate supply.
What It Means for Conventional Board Manufacturers
Substrate capacity is upstream of the system board, not a substitute for it. A packaged accelerator still mounts on a high-layer-count circuit board that distributes power, carries high-speed links and provides the mechanical interface to the chassis. When substrate supply improves, package volumes rise, and demand for those boards rises with them.
The link is direct in another way as well. Both substrates and advanced boards depend on similar capabilities: fine-line imaging, controlled lamination, registration discipline and low-loss materials. A manufacturer competent in one is better positioned in the other than an outsider would be, and several board makers have extended into substrates for exactly that reason.
For a board manufacturer, the practical implication is that capability investment pays across both markets. The skills needed to serve an AI accelerator board and those needed to serve a substrate programme overlap substantially, which improves the return on investing in either.
There is also a qualification cost that is easy to overlook. A new substrate line must be qualified by each customer, a process that involves sample builds, reliability testing and often a period of parallel production. That timeline means the effective supply from a new line lags its installation by many months, and it should be factored into any plan that depends on the expansion.
The Test Step Nobody Plans For
Packaging capacity gains are often described in terms of interposer and substrate output, but test capacity is required at every level: known-good die, known-good interposer, known-good substrate and finally the assembled package. Each test step consumes equipment and time, and each can become the constraint once the others are relieved.
Test is also harder to expand than it appears. High-pin-count test fixtures are specialised, thermal control during test is demanding, and the yield data produced has to be analysed to be useful. Adding testers without adding the engineering to interpret their output produces capacity without improvement.
For suppliers of boards and substrates, this argues for building electrical test capability that produces data rather than only pass or fail results. That data is what allows a manufacturer to improve yield over time, and it is also what customers increasingly ask for when they qualify a partner. It sits naturally within a quality system that treats measurement as part of production.
Materials Remain the Quiet Constraint
Substrate production depends on build-up films, and advanced board production depends on low-loss laminates and very low profile copper foil. Both categories have experienced tight supply and repeated price increases over the past two years, and both come from a limited supplier base.
The consequence is that a capacity plan is only as good as the material allocation behind it. A factory can install equipment and still be unable to run it if the film or laminate is not available. This is why capacity announcements increasingly include material sourcing arrangements rather than only equipment orders.
Buyers should treat material availability as a supply risk in its own right. Asking a manufacturer how many qualified sources it holds for each critical material, and what happens if one of them is interrupted, produces more useful information than an equipment list.
Power and cooling requirements for advanced packaging lines are substantial, and in some regions they have become a constraint on where new capacity can be located. This is a relatively new development for the electronics industry, and it is beginning to influence site selection for packaging and test operations as much as labour cost or logistics do.
There is a scheduling dimension that customers should understand. Because each layer of the stack has its own qualification and lead time, a programme that assumes all layers are available on the same date will be disappointed. Mapping the critical path across interposer, substrate, assembly and test, and identifying which step has the least flexibility, is more useful than negotiating individual lead times.
It is also worth noting that substrate suppliers are increasingly involved in package design discussions, because decisions taken about die placement and bump pitch determine what the substrate must do. Involving the supplier earlier shortens the qualification cycle and reduces the chance of a late change that invalidates completed work.
Planning for the Next Generation
Package sizes continue to grow, and each increase raises the difficulty of every step in the chain. Larger interposers, larger substrates, more dies per package and higher aggregate power all push the same way, toward finer features, better flatness and tighter process control.
Suppliers preparing for that trajectory should be investing in capability rather than in volume alone. The ability to build a slightly larger and slightly finer substrate or board is worth more in this market than the ability to build more of the current generation, because the current generation will not be what ships in two years.
Engaging with customers during package definition, rather than after the design is frozen, is part of the same preparation. A manufacturer who understands what the next package requires can build the process in advance, and that is how a supplier moves from competing on price to being designed in. This is the same manufacturing partnership approach that has served advanced board programmes well, and it applies with even more force when the package itself is the product.